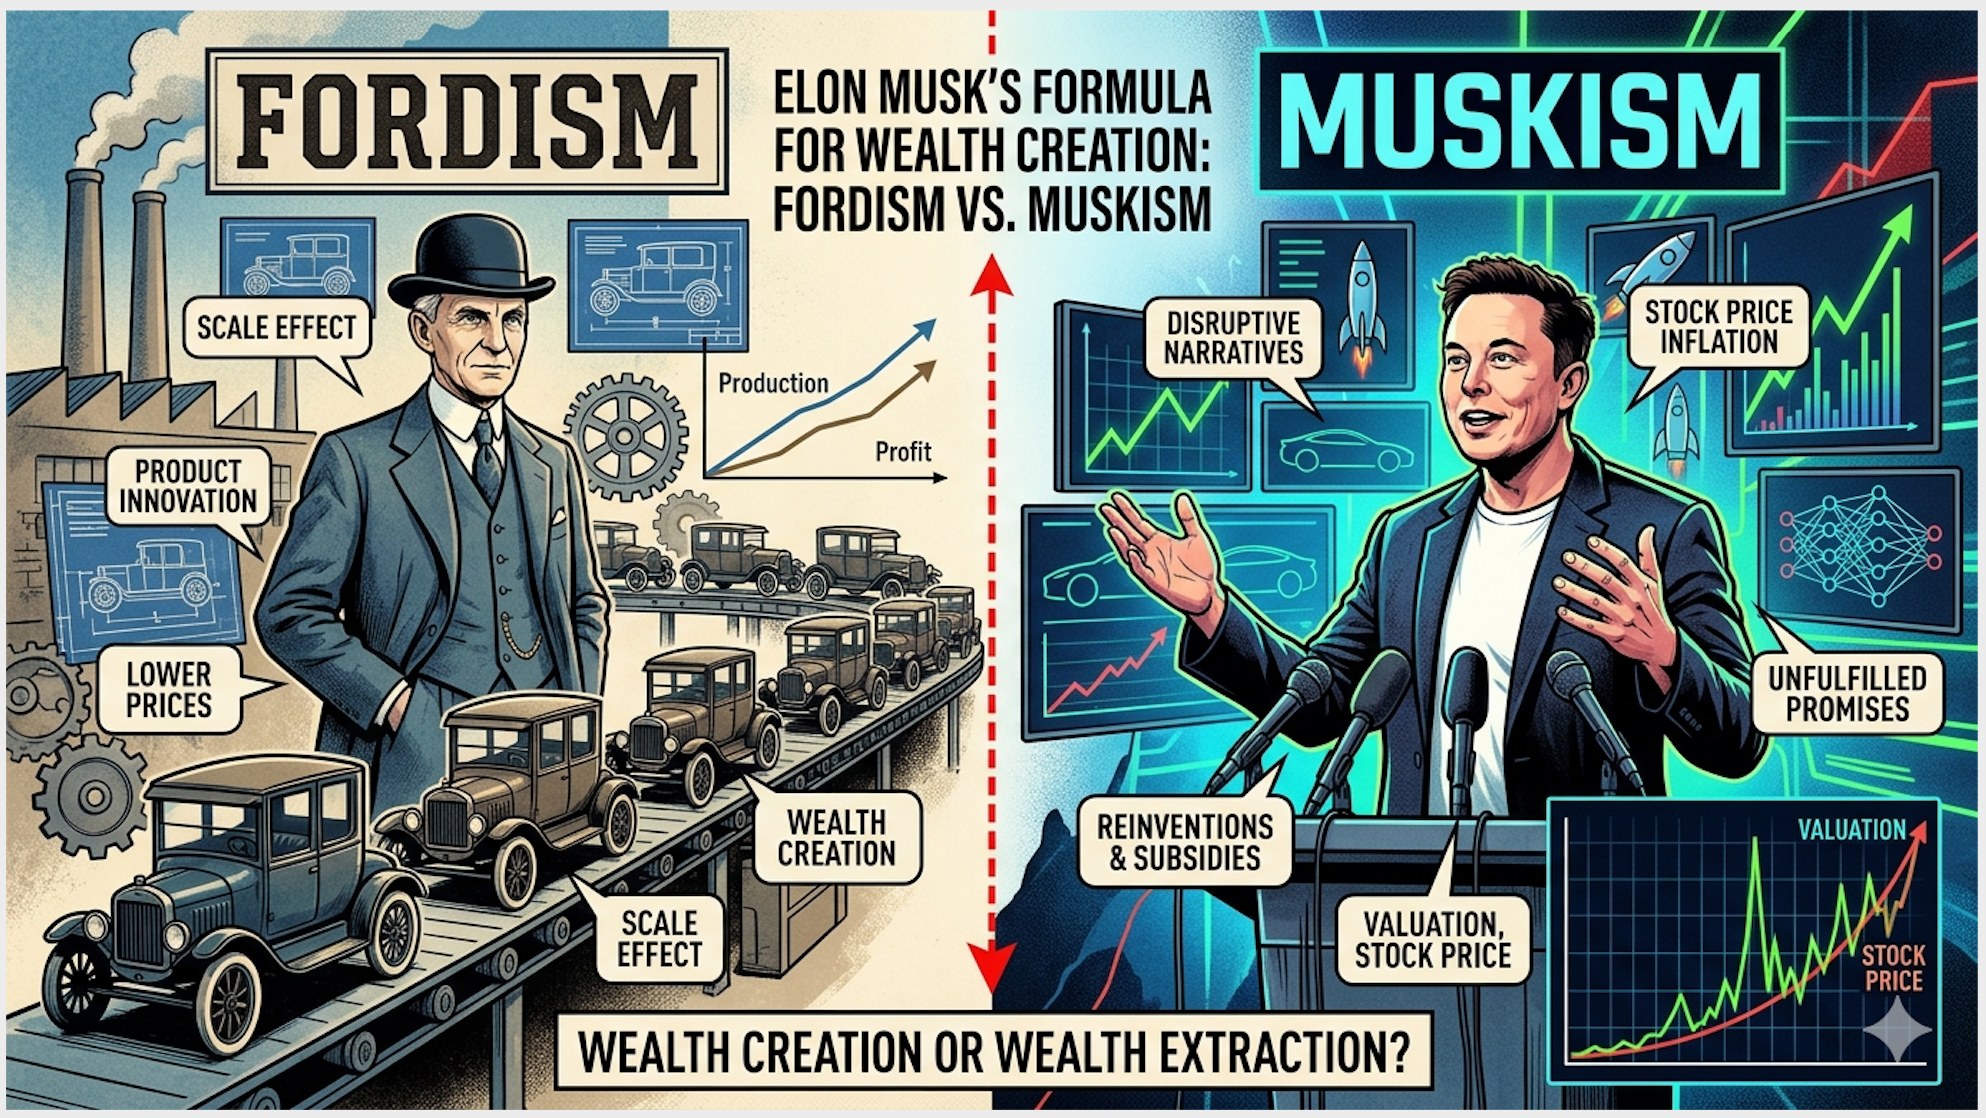
Nobody can ignore Elon Musk’s extraordinary rise in Wealth, reportedly surpassing $800 billion at its peak, which has created Muskism. Moreover, ambitions of reaching a $10 trillion net worth—fuelled by speculation around a potential SpaceX IPO and recurring waves of tech market enthusiasm—raise an unavoidable question: What is Musk’s underlying formula for wealth accumulation, how effective is it, and how does it differ from Fordism?
At the dawn of the 20th century, the world was astonished by the rise of Henry Ford’s wealth, which ultimately provided a defining template for modern Capitalism—widely known as Fordism. This model was grounded in product and Process Innovation to achieve scale economies and sustained profitability. As production scaled, consumers benefited from higher-quality goods at lower prices, thereby expanding markets and generating new wealth. In this way, Fordism transformed capitalism into a powerful engine of value creation driven by tangible innovation.
In contrast, what may be termed “Muskism” appears to follow a different trajectory. Rather than consistently focusing on scale through product and process innovation to generate profits, it emphasizes amplifying market valuation through compelling narratives of Disruptive innovation. These narratives are often reinforced by policy support, speculative capital, and the repositioning of existing technologies as revolutionary breakthroughs. As competitors begin to deliver superior execution in a given domain, the narrative focus shifts to the next frontier—sustaining momentum in valuation growth.
For instance, Musk’s wealth has been significantly driven by Tesla’s soaring valuation amid the electric vehicle (EV) narrative. Yet, as the EV space matures and competition intensifies, the strategic emphasis appears to pivot toward new narratives—such as artificial intelligence and robotics—to further elevate market expectations. This pattern illustrates Muskism as a model centered more on narrative-driven valuation expansion than on fully realized innovation outcomes. Let us examine this dynamic more closely.
Underlying Reality and Thesis Supporting Muskism:
Although the sudden collapse of Kodak’s stock and the rapid rise of small Startups like Apple and Microsoft were striking developments in the 1980s, they were neither isolated nor entirely new. In fact, this pattern had been identified decades earlier by Professor Joseph Schumpeter in the 1940s. Unfortunately, much of management literature overlooked this insight—a gap highlighted by a New York Times op-ed in 2000, which underscored the enduring relevance of his theory of “creative destruction.”
Inventions and innovations are neither static nor infinite. Instead, they evolve over time, typically following an S-curve lifecycle that eventually reaches saturation. Yet, human ingenuity enables us to delve deeper into scientific frontiers, generating new technologies that reinvent existing ones and trigger fresh waves of growth. At the intersection of these successive waves of competition, incumbent firms often falter, while new entrants rise to prominence.
In the 1990s, Professor Clayton Christensen became deeply interested in this phenomenon, particularly the failure of high-performing firms such as Kodak and DEC. He observed that even as leading companies declined, new entrants were successfully offering superior alternatives. He termed this process “disruptive innovation.” The popularization of this concept through his best-selling book The Innovator’s Dilemma fueled both fear and greed among stockholders—individuals and institutions alike. This intellectual shift appears to have contributed to the emergence of what may be called “Muskism”: a strategy of generating wealth through stock ownership driven by expectations of sharp valuation increases under the narrative of disruptive innovation.
Example of Muskism for Gaining Wealth:
One of the most significant engines of Elon Musk’s wealth accumulation has been Tesla. As of mid-2026, Tesla stock ownership accounts for nearly $200 billion of his total wealth. Yet, even 15 years ago, this contribution was negligible, when Tesla’s stock traded at around $1.50—roughly 250 times lower than its current level. Notably, Musk has not earned this wealth through dividends, as Tesla has never paid any. Instead, his wealth from Tesla has been driven almost entirely by the appreciation of its stock valuation.
This raises an intriguing question: what has fueled such extraordinary valuation growth—nearly 250-fold over about 16 years? Has it been driven by high profitability or dominant market share? The answer appears to be no. Rather, it reflects the power of a disruptive innovation narrative that has amplified both fear and greed among investors.
Founded in 2003, Tesla began as a startup aiming to reinvent gasoline-powered automobiles through electric vehicles (EVs). Elon Musk invested early and became CEO in 2008. From the outset, rather than focusing solely on building deeply differentiated, non-replicable technological advantages, the strategy prominently emphasized advancing the EV disruption narrative, supported in part by subsidy-driven market adoption. However, early momentum remained limited due to constraints in core battery technology.
A turning point emerged around 2019, when advances in battery performance crossed critical thresholds, supported by extensive media attention. The Nobel Prize recognition of lithium-ion battery innovation further reinforced this momentum. At the same time, many incumbent automakers were slow to respond decisively, allowing expectations about the future of EVs to accelerate Tesla’s valuation—ultimately propelling Musk to the position of the world’s wealthiest individual.
Similar narrative-driven dynamics appear to extend to Musk’s other ventures, such as SpaceX and Neuralink, further contributing to the expansion of his overall wealth.
Keeping Innovation Promises Undelivered and Moving to Next Narrative: a core strategy of Muskism
As discussed, the core of “Muskism” lies in promoting the belief that a firm will win the race of Reinvention and emerge as the dominant disruptor—thereby inflating valuation and accumulating wealth. However, despite the early success of the electric vehicle (EV) narrative, Tesla has struggled to build deeply non-replicable core technological capabilities in EVs. Instead, it has relied, to a considerable extent, on sourcing key technologies and components from external ecosystems, particularly from Japan and China.
As a result, late entrants—especially Chinese firms—have been rapidly advancing and, in many segments, taking the lead in the global EV race. This shifting competitive landscape appears to have compelled Elon Musk to pivot his narrative from EV disruption toward new frontiers, such as Optimus robots and artificial intelligence.
This strategy of narrative switching has helped sustain—and even elevate—Tesla’s stock price, despite the company not fully delivering on earlier expectations of dominating the global automobile industry through EV disruption.
Hence, it is fair to argue that Muskism is centered on extracting wealth through stock price appreciation driven by disruptive innovation narratives, rather than delivering realized innovation outcomes in the way Fordism did. Moreover, this mechanism of wealth extraction gains further momentum by continually shifting to new narratives, even as previously promoted innovation promises remain only partially fulfilled or unfulfilled.