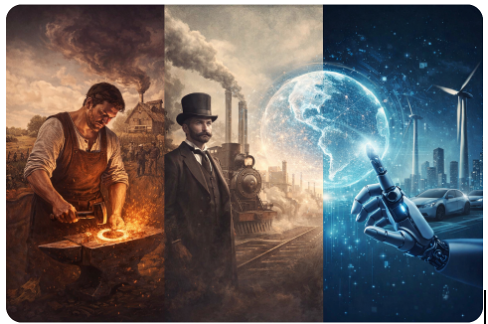
Abstract: China’s transformation from a low-cost manufacturing base to a global leader in electric vehicles, batteries, renewable energy, and high-speed rail challenges long-held assumptions about the supremacy of market economies and democratic institutions in Wealth creation. Over the past 45 years, China has grown far wealthier than many developing peers, notably India, while the epicenter of major Innovation has begun to shift away from Western economies. This article examines this phenomenon through a three-phase framework of wealth creation: pre-industrial Craftsmanship constrained by limited knowledge flows; industrial-era growth driven by science, markets, and entrepreneurship; and the current phase of large-scale Reinvention enabled by machine intelligence and clean energy technologies. Unlike earlier phases, the fourth industrial era requires long-term, system-level coordination that markets and Startups alone struggle to provide. China’s state-led, market-executed model has proven effective in orchestrating such reinvention, raising critical questions about the limits of markets and democracy, requiring institutional adaptation in democratic market economies.
China is no longer merely the “world’s factory” supplying low-cost labor to Western firms. That phase, which helped lift hundreds of millions out of poverty, now belongs to history. Today, China is demonstrating a growing global innovation edge in critical domains such as batteries, electric vehicles, renewable energy systems, mobile communication technologies, and high-speed rail. At the same time, China has become roughly five times wealthier than India over the past 45 years, while the epicenter of major innovation has begun to migrate away from the United States and other Western economies. These developments raise a fundamental and uncomfortable question: are Market Economy and democracy failing as engines of wealth creation in the current technological era, or has the nature of wealth creation itself fundamentally changed? Addressing this question requires a systematic examination of how wealth creation has evolved over time.
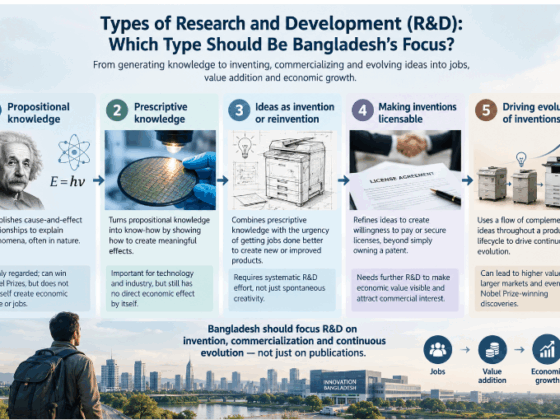
From the very beginning of human existence until the first Industrial Revolution, wealth creation was severely constrained by the nature of knowledge and production. Human progress relied on experiential learning, artisanal craftsmanship, and tinkering-based ideation to create tools for performing diverse tasks. Although innovations were plentiful in number, they were limited in economic impact. The absence of a systematic flow of propositional knowledge—understanding how nature works—and prescriptive knowledge—knowing how to reliably apply that understanding to achieve desired outcomes—meant that innovations could not scale, either in diversity or in economic gravity.
As a result, despite the abundance of tools and localized innovations, the wealth generated from them was modest. Living standards gradually reached saturation and, at best, improved extremely slowly. Comparative advantage during this era arose mainly from natural endowments such as fertile land, climate conditions, access to water, or the availability of specific materials. These advantages enabled localized specialization in production and innovation, which expanded with trade and the division of labor. While trade expansion did generate some wealth, it did not transform productive capacity. This form of growth—later termed Smithian growth—was inherently limited. Millions of cottage-based workshops and farm-centered production units served as the primary sources of wealth, but productivity remained fundamentally constrained.
The second major phase of wealth creation emerged with the systematic growth of economically useful knowledge. This transformation was driven by the adoption of inductive reasoning, the establishment of property rights over capital and ideas, the freedom to profit from innovation, and sustained public investment in scientific and technical knowledge. Newtonian science and mechanical engineering formed the foundation of a new engine of wealth creation, enabling the scaling of pre-industrial inventions and the mechanization of production processes.
Market economy policies and democratic institutions played a decisive role in this phase. They harnessed creativity, entrepreneurial talent, and human aspiration in a competitive global race to evolve inventions and innovations. Speed of delivery, value proposition, and scale of performance became the defining metrics of success. The United Kingdom, followed by continental Europe, took the lead by aligning science, engineering, finance, and markets. Over nearly a century, this alignment generated sustained growth and transformed Europe into the global epicenter of prosperity. The same model later diffused to the United States, Japan, and eventually to Taiwan.
However, this second phase—spanning the first, second, and third Industrial Revolutions from roughly 1750 to 2000—also revealed important limits. Command-driven economies such as the Soviet Union and pre-reform China failed to achieve comparable outcomes. The suppression of entrepreneurial freedom and the absence of incentives to win the global race of innovation resulted in inferior products and inefficient production systems. Similarly, many former colonies, including India, struggled to grow. Their development strategies emphasized labor-based replication through import substitution rather than innovation-driven evolution. As a result, despite political independence, economic convergence remained elusive.
The third phase of wealth creation began with the dawn of the Fourth Industrial Revolution in the early twenty-first century. This phase differs fundamentally from the past. Wealth creation is now driven by large-scale reinvention—replacing existing technological cores with new ones such as machine intelligence, advanced semiconductors, renewable energy, electric mobility, and digitally integrated systems. Reinvention is not incremental improvement; it involves reorganizing entire value chains, infrastructures, and ecosystems. Due to the necessity of technologies from deeper layer of science, the investment need and risk have exponentially grown, reaching beyond the limit of single or a few individuals, startups, and firms.
In this new environment, entrepreneurial talent and individual aspiration, while still necessary, are no longer sufficient to win the global race of reinvention. The risks are higher, the gestation periods longer, and the capital requirements far larger than in previous industrial transitions. Most importantly, reinvention demands system-level coordination across hundreds of firms, research institutions, suppliers, regulators, and infrastructure providers. Consequently, state-led initiatives—executed through profit-seeking competition among private firms—have become critical. Market mechanisms and democratic institutions alone, which were powerful engines in the second phase, increasingly appear inadequate.
This shift helps explain the changing behavior of startups in advanced economies. Due to extremely high technological and financial thresholds, many startups now pursue valuation inflation rather than long-term industrial leadership. Instead of completing reinvention cycles, firms often exit prematurely once valuations peak. The electric vehicle sector provides a telling example. Rather than relentlessly driving cost reduction, performance improvement, and manufacturing scale to establish unassailable global leadership, companies such as Tesla have often prioritized financial narratives and market capitalization over system-level dominance.
Democratic governments face structural constraints in responding to these challenges. In countries such as the United States, political cycles make it difficult to sustain reinvention strategies that require decades rather than election terms. At the same time, these governments are unwilling to allow foreign reinvention waves—particularly from China—to rapidly displace domestic incumbents. As a result, policy responses increasingly focus on creating barriers rather than accelerating reinvention. The shift during the Trump administration from facilitating electric vehicle adoption to protecting gasoline vehicles and oil trade illustrates this defensive approach.
Germany’s experience further highlights the problem. Despite possessing world-class engineering firms in automobile innovation and manufacturing, Germany has struggled to coordinate a synchronized response across automakers, battery suppliers, energy systems, and regulatory frameworks. Fragmentation and institutional inertia have undermined its ability to compete effectively in the electric vehicle race.
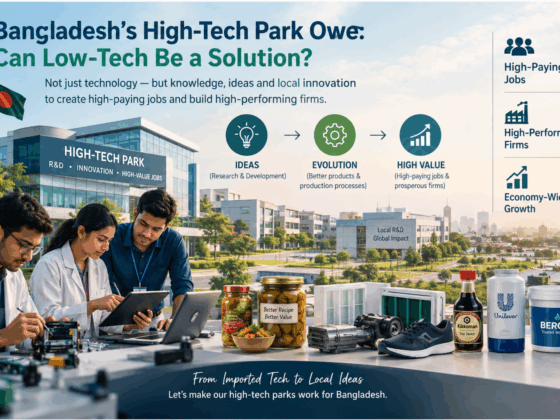
China’s trajectory stands in sharp contrast. Through state-led initiatives implemented in partnership with competitive private firms, China has orchestrated large-scale reinvention across multiple sectors. In electric vehicles, renewable energy, batteries, mobile phones, and high-speed rail, China has aligned long-term national objectives with industrial policy, financing mechanisms, infrastructure development, and firm-level competition. While not without inefficiencies or risks, this model has enabled China to capture learning curves, scale advantages, and ecosystem control faster than market-driven systems alone.
This does not imply that markets and democracy are inherently failing. Rather, it suggests that the nature of wealth creation has changed. Institutions that were sufficient for innovation-driven growth during the second phase are no longer adequate for reinvention-driven growth in the third phase. Wealth creation in the twenty-first century depends on the ability to orchestrate long-term, system-level transformations—something that China has, so far, been better positioned to do.
In conclusion, the rise of China as a global innovation leader is not an anomaly but a reflection of a deeper structural shift in how wealth is created. As the epicenter of innovation migrates, the critical question for democratic market economies is not whether they should abandon their institutions, but whether they can adapt them to the demands of large-scale reinvention. Without such adaptation, the future of global prosperity may increasingly be shaped elsewhere.
Key messages:
China’s rise reflects a structural shift in wealth creation, not just cost advantage.
The transition from low-cost manufacturing to leadership in EVs, batteries, and renewables signals mastery of large-scale reinvention, not labor arbitrage.
State-led, market-executed coordination is reshaping global prosperity.
China’s ability to align long-term state vision with competitive private firms gives it an edge in emerging wealth-creation waves.
Market economy and democracy were sufficient for past innovation, but not for today’s reinvention.
Institutions that powered industrial-era growth struggle with high-risk, long-gestation, system-level technological transitions.
The Fourth Industrial Revolution is driven by replacing technology cores, not Incremental innovation.
Success now depends on reorganizing entire ecosystems—value chains, infrastructure, regulation, and finance—simultaneously.
Startup-led and valuation-driven models increasingly fail to deliver global leadership.
Many firms exit reinvention races prematurely, prioritizing financial returns over completing cost-performance dominance.